A reader-requested guide to one named service, assessed against enrollment, full cost and record-verification decisions. Vendor claims are attributed; no ranking, endorsement or guaranteed outcome.
Commercial status: There are no affiliate links in this edition. No verified commercial arrangement with Esusu or its partners is used in this article; providers did not pay for inclusion or approve the copy.
Your rent payment and your credit report may tell different stories. Before paying for Esusu, check whether your property already includes its reporting service. This guide helps you compare the enrollment route, cost and records you will need.
Esusu says it reports on-time rent to Equifax, Experian and TransUnion. Reporting adds information to a credit file; it does not promise a higher score or an approved application. The details below concern US renters and were checked on October 25, 2026.
Check the property route before paying

Read infographic as text
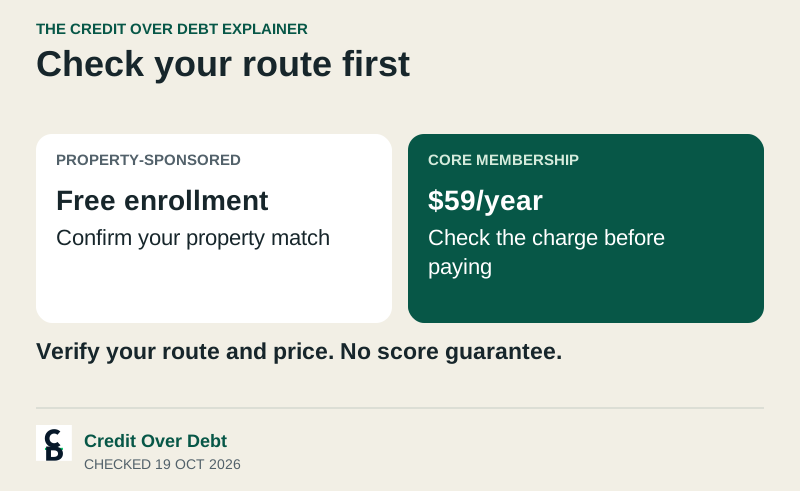
- Property-sponsored route: Esusu advertises free enrollment for partnered properties.
- Otherwise: Core Membership is advertised at $59 a year.
- Confirm the property match and actual charge. Reporting does not guarantee a score increase.
Esusu's renter page says its app checks your address for a property partnership. It advertises free enrollment at partnered properties and Core Membership at $59 a year otherwise. It also says rent data comes from the property system or a linked bank account, without changing how you pay rent.
Ask your property manager whether reporting is already included in your lease or resident benefits. Confirm the name of the service, who pays and whether you have already been enrolled. Save the answer beside the enrollment screen. If the two disagree, resolve that discrepancy before buying another subscription.
The current Esusu terms make reporting conditional on the renter and property qualifying and on obtaining verifiable data. An address lookup is a starting point, rather than confirmation that every payment can be reported.
Write down the annual commitment
Keep the reporting benefit and the renewal reminder together. If your property starts paying for reporting after you have bought a membership, ask which paid features remain and whether the subscription continues. Do not assume the new property benefit cancels an existing charge; obtain a confirmation for your own account.
The advertised annual price is about $4.92 per month when divided by 12. That arithmetic helps with budgeting; it does not establish a monthly billing option. Write down the actual amount due today, any tax, the renewal date and the cancellation route shown for your account.
Esusu's terms say paid subscriptions renew automatically at the then-current fee unless canceled. Direct subscribers can request cancellation through support; partner registrations use the partner's process. Unused subscription periods do not carry a promised refund.
Here is an illustrative budget check, using invented circumstances: you have $80 left after rent and essential bills. A $59 upfront charge leaves $21. The price might look small as a monthly equivalent while taking most of that immediate cushion. Decide using money available on the charge date, rather than an expected score benefit.
You can postpone a paid subscription while asking about the property route. Do not add a credit payment to fund reporting. Keep a cancellation confirmation if you stop the service; deleting an app should not be your record that billing has ended.
Keep three commitments on separate lines
Make a private enrollment note with one line for rent reporting, one for any paid membership and one for optional financing. Against each line, write the named company, what you agreed to, the charge date and how to end that particular arrangement. Leave a field blank when the screen has not answered it.
This is an organizing method, not a claim that every renter has three contracts. Its purpose is to stop a free reporting benefit, a subscription and a repayment schedule being treated as one promise. Ask support to identify which line a confirmation or cancellation concerns. Record the answer before assuming another commitment has ended.
If a property supplies reporting, compare its confirmation with any payment screen before enrolling again. Do not treat a second subscription as a way to obtain a second score increase. If you cannot establish who pays or what is already active, pause the purchase and request one clear explanation.
Match the rent record to your documents
Prepare a compact record from documents you already have. List the lease address, your name as shown on the lease, payment dates and the amounts paid. Keep receipts or the property ledger alongside bank entries. This gives you something specific to compare with a reported rental account.
Esusu advertises backfill of up to 24 months of available on-time payments on the current lease, without an extra backfill charge. That is a maximum and depends on available history. It is not a promise to reconstruct every previous tenancy.
If you share rent, pay in several transfers or receive a concession, ask how that arrangement will be represented. Do not assume a bank transfer identifies the correct tenant or rental month. Mark an unexplained amount as unresolved and ask for clarification before accepting it.
Esusu's privacy policy describes collecting identity and credit-related information and, where needed, accessing bank-account information through a third-party processor to identify rent. Read the connection screen and that processor's terms before consenting.
Use the official account route for enrollment. Keep sensitive identifiers out of an ordinary message asking your landlord whether the benefit exists. A useful first question does not require sending your entire bank statement or Social Security number.
Keep reporting separate from the score you see
FICO explains that reported rental data is included in FICO Score 9, 10 and 10T. Its guidance also shows why model versions matter: rent reporting does not affect every FICO version in the same way. A record reaching a bureau and a lender using a particular score are separate checks.
When comparing a score before and after enrollment, note the bureau, model and observation date. Compare the same model where possible. A screenshot from a different app is not enough to identify what changed, and another account may have changed during the same period.
Esusu advertises an average 53-point increase for active renters at active properties through Q4 2025. Its methodology treats people without a starting score as having zero. This is a vendor-reported comparison, not a forecast for you or proof that reporting caused the whole change.
Do not subtract a promised number from a target score or buy the service expecting that number. First decide whether an accurate rental history is useful for your purpose. If an application is imminent, ask the provider which report and score it uses; reporting cannot replace its eligibility checks.
Understand what positive-only reporting does not cover
Esusu says it does not report missed or late rent through its rent-reporting service. Separately, CFPB guidance explains that rental-payment and related collection information can appear in consumer reports. Esusu's policy does not prevent another company from reporting a debt or a landlord from using a tenant-screening report.
Keep paying under your lease. If rent becomes unaffordable, contact the property manager about a documented arrangement before assuming any app changes the obligation. Reporting and resolving a payment shortfall are different tasks.
Optional financing also needs its own review. Esusu's Affirm page describes availability at participating properties, subject to eligibility, and says Affirm reports payment plans including past-due payments. Do not apply the positive-only rent-reporting promise to a financing agreement.
Read the full repayment schedule before using a rent-payment feature. Identify who you would owe, what leaves your account before the next payday and what happens if a payment is missed. A reporting subscription should not become a reason to take on a loan.
Check the bureau entry and correct a specific error
After Esusu confirms that data was submitted, check the relevant credit reports. Compare the rental account with your saved record: identity, address, dates and payment amounts. Ask support about a missing entry instead of treating an app status as proof that a bureau received it.
The CFPB says credit-report errors should generally be disputed with both the reporting company and the business that supplied the information. Explain what is wrong and provide copies of supporting documents. Keep the report, your dispute and the response together.
Make the question narrow: a payment recorded for the wrong month, an incorrect amount or an account belonging to someone else. That is easier to investigate than asking why a score did not rise. Our credit-report correction guide helps organize that record.
Esusu's terms say Passport is an informational rental-history feature, not a consumer report or a substitute for one. They prohibit using it to establish eligibility for credit, housing, employment or other Fair Credit Reporting Act (FCRA) purposes. Do not present it as an application approval document.
Leave with one confirmed answer
Start with a message to the property manager: “Is Esusu rent reporting included for my lease, and will I pay anything for it?” Save the reply. That one answer tells you whether to investigate an existing benefit or compare a new paid commitment.
If the benefit is already included, focus on the accuracy of the record. If payment is required, keep the charge, renewal terms and data permissions together before deciding. An unresolved fee or unexplained record is a reason to pause and ask, rather than guess.
From comparison to calculation
Check the terms in the offer you actually receive.
Credit Over Debt’s Offer X-Ray compares the amount financed, fees, payment schedule and modeled cost using the figures you enter.
Open the free toolkitPrimary sources and product pages
- Esusu: Esusu for renters: membership and questions (checked 2026-10-25)
- Esusu: Rent reporting and outcome methodology (checked 2026-10-25)
- FICO: How to add rent payments to your credit reports (checked 2026-10-25)
- Consumer Financial Protection Bureau: Does late rent affect my credit score? (checked 2026-10-25)
- Consumer Financial Protection Bureau: How do I dispute an error on my credit report? (checked 2026-10-25)
- Esusu: Terms and conditions: fees, cancellation, reporting and Passport (checked 2026-10-25)
- Esusu: Privacy policy, updated March 12, 2026 (checked 2026-10-25)
- Esusu: Affirm payment option and reporting disclosure (checked 2026-10-25)
Product details last checked Oct 25, 2026; next scheduled review Nov 24, 2026. This US-focused guide is educational information, not individualized financial, legal or tax advice. Product terms, offers and eligibility can change.